Forschung
Im Folgenden finden Sie eine Übersicht der Forschungsfelder sowie eine Auswahl an zentralen Publikationen der Arbeitsgruppe um Prof. Dr. Andreas Rathgeber. Eine vollständige Liste der Veröffentlichungen finden Sie hier.
Applied Data Analysis
Economy of Commodity Markets
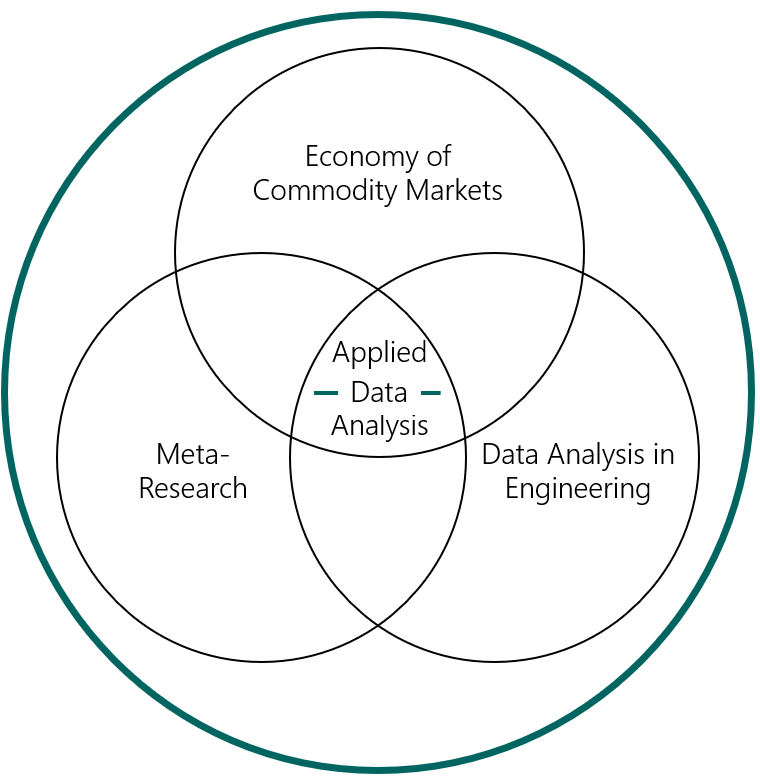
Die Arbeitsgruppe von Prof. Dr. Andreas Rathgeber widmet sich im Rahmen interdisziplinärerer Projekte verschiedenen Fragestellungen im Bereich Economy of Commodity Markets. Im Fokus stehen die Auswirkungen des Klimawandels und der Energiewende auf Rohstoff- und Strommärkte.
-
Drivers of Emission Prices - Disentangling Fundamental Shocks in the European Carbon Market
Maulberger, A.; Rathgeber, A.
Working Paper -
Identifying Drivers of Price Dynamics in the Cocoa Market
Schischke, A.; Ligorati, M.; Schmid, F.; Rathgeber, A.
Working Paper -
Spillover effects in electricity markets
Schischke, A.; Rathgeber, A.Working Paper -
Commodities and monetary policy - the role of interest rates revisited
Schischke, A.; Rathgeber, A.Working Paper - The three co's to jointly model commodity markets: co-production, co-consumption and co-trading
Schischke, A.; Papenfuß, P.; Rathgeber, A.
Empirical Economics, 66, 2024, pp.883-925. -
Rebalancing effects of commodity indices on open interest, volume and prices
Schmid, F.; Mayer, H.; Wanner, M.; Rathgeber, A.The European Journal of Finance 29, 1187-1206 (2023)
Data Analysis in Engineering
Im Bereich Data Analysis in Engineering beschäftigt sich die Arbeitsgruppe mit der Aufbereitung, Modellierung und Interpretation technischer Daten unter Anwendung statistischer Methoden. Ziel ist es, ein tiefgehendes Verständnis technologischer Prozesse und Systeme zu entwickeln, um so zur Steigerung der Effizienz, zur Förderung von Nachhaltigkeit und zu einer zirkulären Nutzung von Rohstoffen beizutragen.
- The Impact of Photovoltaic Module Recycling on Silver Market Dynamics: Analysis and Projections
Straub-Mück, M.; Schischke, A.; Rathgeber, A.
Working Paper - MXene-Based Room-Temperature NO2 Gas Sensors: A Meta-Analysis
Khort, A; Geyer-Klingeberg, J.; Rathgeber, A.; Barg, S.
Advanced Science, e77530 (2026) - Degradation of lithium-ion batteries: a meta-analysis
Ligorati, M.; Geyer-Klingeberg, J.; Rathgeber, A.
Chemical Engineering Journal, 174528 (2026) - Determinants of the long-term degradation rate of photovoltaic modules: A meta-analysis
Straub-Mück, M.; Geyer-Klingeberg, J.; Rathgeber, A.
Renewable & Sustainable Energy Reviews, 216, 115697 (2025) - Sustainable energy transition and its demand for scarce resources: insights into the German Energiewende through a new risk assessment framework
Schischke, A.; Papenfuß, P.; Brem, M.; Kurz, P.; Rathgeber, A.
Renewable & Sustainable Energy Reviews, 176, 113190 (2023)
Meta-Research
Eine weitere Gruppe von verwendeten Methoden ist die Meta-Analyse als übergeordnete „Analyse der Analysen“. Ursprünglich aus der medizinischen Forschung mit dem Ziel der Steigerung der Teststärke von Medikamentenstudien mit wenigen Probanden entstanden, stellt die Meta-Analyse eine statistische Zusammenfassung von Primäruntersuchungen dar. Aufgrund der rasanten Zunahme empirischer Publikationen und der Heterogenität der Ergebnisse in vielen Forschungsfeldern, wächst auch die Bedeutung von Ansätzen zur Aggregation der Befunde aus unterschiedlichen Primärstudien. Die Meta-Analyse erlaubt eine solche systematische Sekundärdatenanalyse sowie eine Identifikation und statistische Quantifizierung der Stärke des Einflusses von Unterschieden im Studiendesign auf die Studienergebnisse. Ferner ermöglicht sie die Messung und Korrektur verzerrender Effekte, wie der sogenannten Publication Bias oder der Missspezifikation der Modelle der Primärstudien. Innerhalb der Meta-Analyse werden verschiedene Methoden, darunter univariate/multivariate Meta-Verfahren, Meta-Regressionen und meta-analytische Strukturgleichungsmodelle angewendet.
Die Arbeitsgruppe um Prof. Rathgeber überträgt die Methodik der Meta-Analyse auf Fragestellungen im Bereich Economy of Commodity Markets und Data Analysis in Engineering, wie zum Beispiel der Einfluss von Rohstoffpreisschocks auf Aktienkurse oder die Degradation von Photovoltaik Modulen.
Im Rahmen dieses Forschungsfelds kooperiert das Team mit internationalen Wissenschaftlern des Meta-Analysis of Economics Research Networks ( MAER-Net).
- Guidance for the Use of AI in the Meta-Analysis of Economics Research
Cook, N.; Bartoš, F.; Bom, P. R. D.; Gechert, S.; Kantová, K.; Geyer-Klingeberg, J.; Havránek, T.; Irsova, Z.; Luskova, M.; Opatrný, M.; Prante, F.; Rachinger, H. J.; Stanley, T. D.
Journal of Economic Surveys, Forthcoming, 2026 - Reporting Guidelines for Meta‐Analysis in Economics—Updated for AI
Cook, N.; Bartoš, F.; Bom, P. R. D.; Gechert, S.; Kantová, K.; Geyer-Klingeberg, J.; Havránek, T.; Irsova, Z.; Luskova, M.; Opatrný, M.; Prante, F.; Rachinger, H. J.; Stanley, T. D.
Journal of Economic Surveys, Forthcoming, 2026 - Determinants of the long-term degradation rate of photovoltaic modules: A meta-analysis
Straub-Mück, M.; Geyer-Klingeberg, J.; Rathgeber, A.
Renewable & Sustainable Energy Reviews, 216, 115697 (2025). - Reporting Guidelines for Meta-Analysis in Economics
Havranek, T.; Stanley, T.D.; Doucouliagos, H.; Bom, P.; Geyer-Klingeberg, J.; Iwasaki, I.; Reed, R.W.; Rost, K.; Aert, R.C.M.
Journal of Economic Surveys, 34(3), 2020, pp. 469-475. - Meta-analysis in Finance Research: Opportunities, Challenges, and Contemporary Applications
Geyer-Klingeberg, J.; Hang, M.; Rathgeber, A.
International Review of Financial Analysis, 71, 101524, 2020. - Corporate financial hedging and firm value: a meta-analysis
Geyer-Klingeberg, J.; Hang, M.; Rathgeber, A.
European Journal of Finance, 27, 2020, pp. 461-485 - Global Climate Impacts of Agriculture: A Meta-Regression Analysis of Food Production
Gaugler, T.; Stoeckl, S.; Rathgeber, A.
Journal of Cleaner Production, 276(122575), 2020. - Measurement matters - A meta-study of the determinants of corporate capital structure
Hang, M.; Geyer-Klingeberg, J.; Rathgber, A.; Stöckl, S.
Quarterly Review of Economics and Finance, 68, 2018, pp. 211-225.
Work in Progress
- When Geopolitical Escalation Hits Oil: An AI-Enhanced Directional News-Based Index of Perceived Oil-Supply Risk
Caldara and Iacoviello’s (2022) broad Geopolitical Risk index (CI-GPR) has become a benchmark
measure in oil-market research, yet its return effects remain unstable, reflecting its aggregation of shocks
with opposing oil-market implications. We develop Oil-GPR, an AI-based news index of perceived
geopolitical risks to oil supply. The index preserves CI-GPR’s newspaper share-of-coverage logic but
restricts attention to news linking geopolitics to physical oil supply, transport, infrastructure, or trade
flows. An AI-based full-text classifier screens keyword hits for substantive oil-supply relevance and
distinguishes escalating from deescalating news, realized disruptions from threats, and physical
disruptions from policy restrictions. Only 16.6% of keyword hits are retained as substantive oil-supply-
risk news; the gap between keyword-based and AI-validated attention varies substantially over time.
Keyword noise is therefore not removable by simple rescaling, a concern relevant for news-based indices
beyond oil markets. Oil-GPR is constructed as a directional measure rather than a one-sided adverse-
news count. Deescalating developments offset escalating supply-risk coverage rather than being ignored
or pooled with adverse news. This directional structure has broader relevance for news-based risk
measurement, where adverse-topic attention may coexist with risk-reducing developments. Empirically,
Oil-GPR maps sharply into monthly Brent futures excess returns, while CI-GPR does not. Oil-GPR
alone explains 5.2% of monthly return variation and remains positive in joint specifications. Subindices
and IRFs based on a SVAR indicate that oil markets price not only realized disruptions but also threats
and policy restrictions that change perceived future availability. Oil-GPR therefore provides a new oil-
specific geopolitical-risk proxy for empirical oil-market research.
Downloads
Please find the latest version of the working paper, along with the Oil-GPR Index and its subcomponents, attached below.